AI Based Capital Management
Position sizing services, portfolio risk monitoring, drawdown controls and multi-strategy allocation tools that apply the limits your risk team sets, explain every calculation and leave the final call with people.
What is AI capital management?
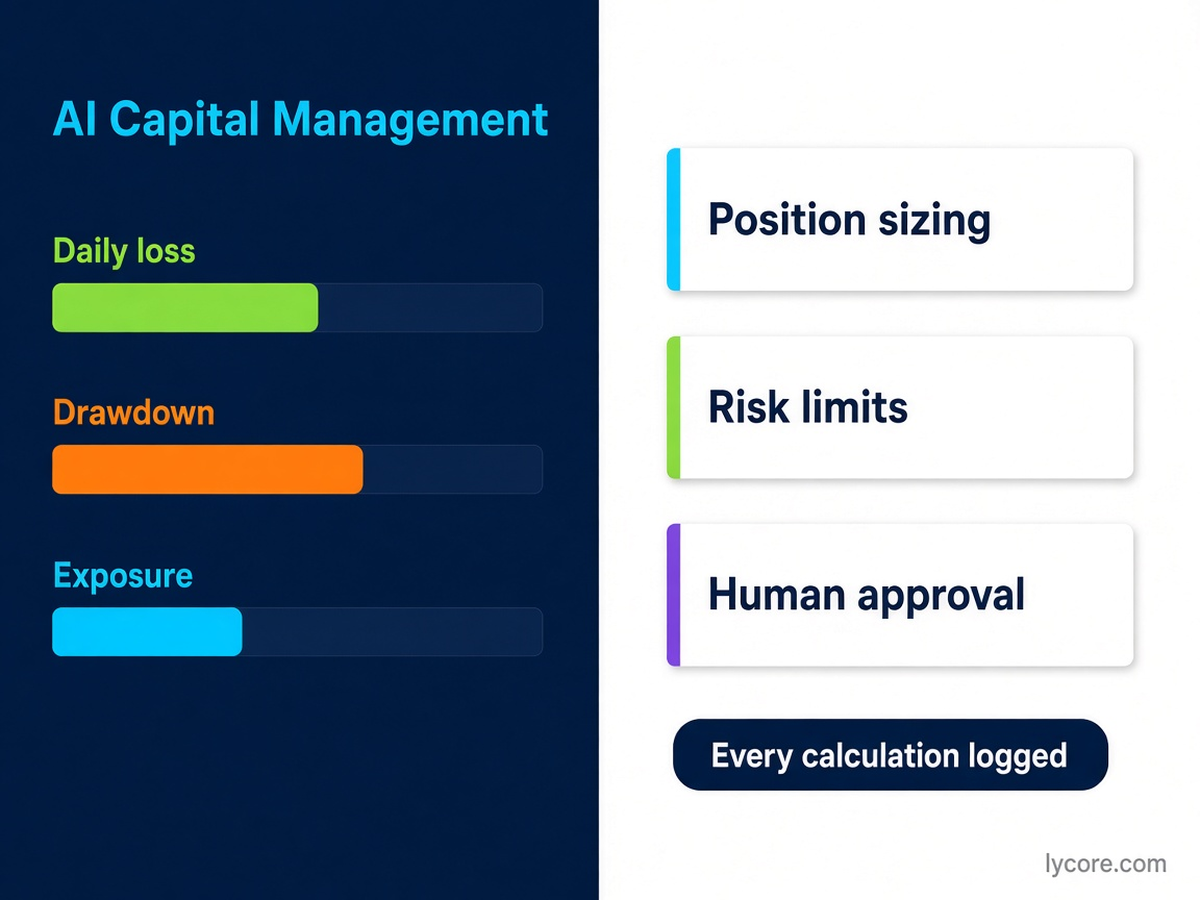
AI capital management is software that calculates how much capital each position, strategy or account should use under rules a firm defines, and monitors risk against those rules in real time. Models help estimate volatility, correlation and market regime. Risk managers set the limits and approve any action outside them.
How much to allocate to each strategy, position or asset class, and how to adjust as conditions change, is one of the most important decisions in trading. It is also one where inconsistency creeps in: limits applied differently on a busy day, exposure that nobody totaled across desks, drawdown rules that exist on paper only. Software makes those rules consistent and visible.
Our approach combines classical allocation methods, such as fractional Kelly sizing, risk parity and mean-variance optimization, with machine learning for estimating inputs and detecting regimes. We build these as part of our AI development services, as standalone tools for portfolio managers or as components of a wider trading platform.
Capital management capabilities we build
Each component takes data from your order management system, broker or exchange, and applies rules your risk team owns.
Dynamic position sizing
A service that takes signal confidence, volatility, correlation with open positions and the remaining risk budget, applies volatility targeting or fractional Kelly with shrinkage, and returns a size with its full calculation basis.
Portfolio risk monitoring
Real-time VaR and CVaR, gross and net exposure, factor and sector concentration, correlation, leverage, margin use and currency exposure, with thresholds your risk managers configure.
Tiered drawdown controls
Soft limits that scale positions down, medium limits that move to defensive settings, and hard limits that halt trading for human review, measured as static or trailing drawdown.
Multi-strategy allocation
Risk parity and constrained mean-variance optimization across strategies, with capacity limits and minimum and maximum allocations, producing proposals for your investment committee to approve.
Regime detection
Hidden Markov models or clustering on volatility and correlation features that label current market conditions, used as an input your risk team can choose to apply, not as a forecast.
Account rule engines
Daily loss limits, maximum drawdown, profit targets and consistency checks evaluated across many trader accounts, as used by prop firms and funded trader programs.
How a capital management system fits your stack
Capital management sits between your signals and your orders. It needs current positions, current prices and a clear policy, and it must explain every number it produces.
- Inputs. Positions and fills from your order management system, broker or exchange, live prices, and signal outputs from your research layer.
- Risk engine. Recalculates exposure, limits and sizing on every relevant update, in one server-side service that is the single source of truth.
- Policy layer. Limits and sizing rules stored as versioned configuration, changed only through an approval step.
- Actions. Alert, scale down, block new orders or halt, each allowed only within the ranges your team has pre-approved.
- Explanations and logs. Every calculation is stored with its inputs, so any sizing or allocation can be reviewed later.
Typical stack
- Calculation: Python, NumPy and pandas.
- Optimization: cvxpy for constrained allocation problems.
- Models: scikit-learn and gradient boosting for estimates and regimes.
- State: Redis for live exposure, PostgreSQL for history and audit.
- Dashboards: Risk views with limit bars and alerts.
Transparency and human oversight
Capital management software touches every position, so its controls have to be stricter than the strategies it governs.
- Every decision is logged. Inputs, calculation basis and output are stored for each sizing and allocation decision.
- Automated actions stay inside approved ranges. Anything outside them requires a person to approve it.
- Limit changes are versioned. Who changed what, when and why is recorded, and old versions can be restored.
- Models are documented and validated. Estimation models follow your firm’s model risk policy, with documented assumptions and periodic review.
- No return promises. Allocation tools estimate risk; they do not predict returns, and we make no performance claims.
Fiduciary and regulatory questions about allocation and risk policy belong with your counsel and compliance team, and we build to the requirements they set.
Account-level risk rules in LyTrade
LyTrade, one of our working apps, is the software a proprietary trading firm runs on. Trading in it is simulated with sandbox payments, and it shows account-level capital rules enforced by a server-side engine.
LyTrade
Trading: software a prop firm runs on, with simulated trading
Operators configure each plan’s rules, traders see every limit tracked live, and the firm sees risk across all accounts.
- Configurable rules. Defaults include a daily loss limit of 5% of the higher of the day’s starting balance or equity, and maximum drawdown of 10% of the initial balance, static or trailing.
- Rules snapshot. Each account keeps the rules it was bought with; plan changes apply to new purchases only.
- Risk calculator. Turns a risk amount, as a percent of equity or in USD, and a stop distance into a lot size.
- Firm-wide view. Open exposure by instrument and accounts near breach, defined as within 30% of a hard loss limit.
- Consistency flags. A single day above 40% of total profit is flagged in payout review, and a person makes the payout decision.
These are the same rule types we build into capital management systems for live trading.
Related reading
Technical guides from our blog on risk, compliance and trading systems.
Real-time compliance risk dashboard: build guide
Data science trading systems: architecture lessons
AI-powered trading software and algorithmic bots
Algorithmic trading platforms: backtesting and live execution
AI-driven compliance monitoring in regulated industries
AI trading strategy: faster insights from your data
More trading guides: AI stock research, AI signal generation and automated trading bots and tools. Back to the AI for trading overview, see every AI for industries guide, or read how we build and price this work on our AI development services page.
Frequently asked questions
Will AI capital management improve our returns?
We do not make that claim. Capital management software applies sizing rules and risk limits consistently, calculates exposure in real time and shows every calculation, which helps your team see and control risk. Whether that leads to better results depends on your strategies, your rules and the market. The models we use estimate inputs such as volatility and correlation; they do not predict returns, and allocation decisions stay with your portfolio and risk managers.
Can risk managers override the system?
Yes, and the system is designed for it. Every sizing output arrives with its calculation basis, so a risk manager can see why a number was produced and replace it when they know something the model does not. Automated actions only happen inside ranges your team has approved; anything outside those ranges waits for a person. Overrides and limit changes are recorded with who made them, when and why.
Can it handle prop firm style account rules?
Yes. Daily loss limits, static or trailing maximum drawdown, profit targets, minimum trading days, maximum position size and consistency checks are all rule types we build into account-level engines. Each account can keep the rule set it started with, so changing a plan does not change existing accounts. Our LyTrade app shows this pattern working in a simulated environment, with rules evaluated on every price tick and fill.
How much does an AI capital management system cost?
We work at USD 25 per hour offshore, on a fixed project price or on a monthly retainer. As an indicative guide, a position sizing service or risk dashboard on top of an existing platform usually falls in the USD 7K-15K band, portfolio risk monitoring with tiered drawdown controls in the USD 15K-30K band, and multi-strategy allocation with optimization, approvals and full audit in the USD 30K-50K band or above USD 50K. Market data, exchange and AI model usage fees are paid to those providers, and we estimate them before the build starts.
Building AI capital management tools?
Tell us about your strategies, limits and current risk tooling. We will tell you what to build, what it would cost and how long it would take.
Talk to Lycore